

Open a bottle of soda that’s been shaken and the CO₂ doesn’t wait for you. It comes out in a rush. A hiss, a surge of foam, all of it driven by pressure that took no effort on your part to create. Then the drama ends. But the bottle isn’t finished releasing gas; it’s just releasing it slower. Bubbles keep rising for minutes, then hours, fewer and fewer, until what’s left is a full bottle of flat soda. Nobody drank it. Nothing was poured out. The bottle simply lost the thing that made it lively. Oil and natural gas wells do the same thing. That ordinary physical fact — the “decline curve” — shapes nearly every investment decision affecting America’s energy security.
What is a decline curve?
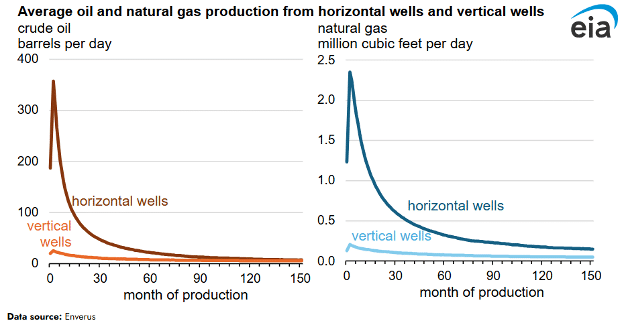
A decline curve plots a well’s production over its lifetime. New wells produce the most oil or natural gas right out of the gate, when reservoir pressure is highest and resources can move through rock most easily. As pressure drops and the easiest-flowing oil and gas gets pulled out, production steadily tapers like the bubbles thinning out in that opened bottle.
Nearly all U.S. production now comes from shale wells, drilled horizontally and hydraulically fractured. These wells open at their peak production and fall hard: a typical well loses more than half its output in the first year, then keeps sliding before settling into a long, slow tail that can run for decades. A well drilled today will produce most of its lifetime oil within its first three or four years. This isn’t a niche detail for petroleum engineers. It’s the single physical fact that explains why “flat production” is an active verb, not a passive state.
Running to stay in place
Here’s the part most people miss: “holding production flat” doesn’t mean a company is coasting. It means the company must sprint on a treadmill just to stay in place.
Every existing well produces a little less oil today than it did yesterday. To offset that decline, companies have to constantly drill new wells, complete them through hydraulic fracturing, fix pumps, manage water, and run workovers on old wells — all just to keep the topline production number flat. Zero growth in the production data can still mean maximum effort behind the scenes. In 2024, U.S. producers invested over $145 billion to drill over 14,500 new wells, with oil production growing by just under 2%.[1]
That’s also why American oil and natural gas producers keep investing in innovation to make each well more efficient. The U.S. is producing more energy today than at any point in its history, even as the number of rigs running has fallen from its shale revolution peak of more than 1,900 in the fall of 2014 to roughly 590 rigs nationwide in August 2026.[2]

Look at just the newest sliver on the chart above — the red band — and the scale of that impact comes into focus. Wells brought online in 2024 alone accounted for roughly 38% of that year’s Lower 48 crude oil production and about 23% of natural gas production. If drilling had suddenly stopped, existing wells alone could not have made up the difference. Production would have fallen by roughly that much within the same year, a shock that would be devastating for the U.S. and global economy. That is exactly why so much continuous investment goes into new wells.
The takeaway
This matters for policy because energy supply often gets treated like a thermostat: turn up prices, production goes up; turn down prices, production goes down. That’s true directionally over the long run. But it skips the lag time. New production needs capital, rigs, crews, steel, sand, water, permits, and pipeline capacity plus confidence that the investment still pencils out a year or two from now, not just today.
Energy supply is physical, not just transactional. It runs on geology, pressure, equipment, and time, and all of that comes with built-in momentum and lag. Supply’s ability to respond to rising demand is limited by geology, physics, and capital investment, not just price. What looks like “flat” production from the outside is the result of large, continuous reinvestment just to hold steady. Any growth on top of that takes significant additional time and capital.
That’s the part the decline curve makes impossible to ignore: maintaining world-leading production levels requires massive investment. Growing it, or getting it back online after a shock, takes more than a short-term market signal. It takes time, investment, and a lot of unglamorous oilfield work most headlines never mention.
[1] Rystad Energy, Economic Impact of US Independent Operators, August 2025
[2] North American Rig Count, Baker Hughes, Accessed August 2026